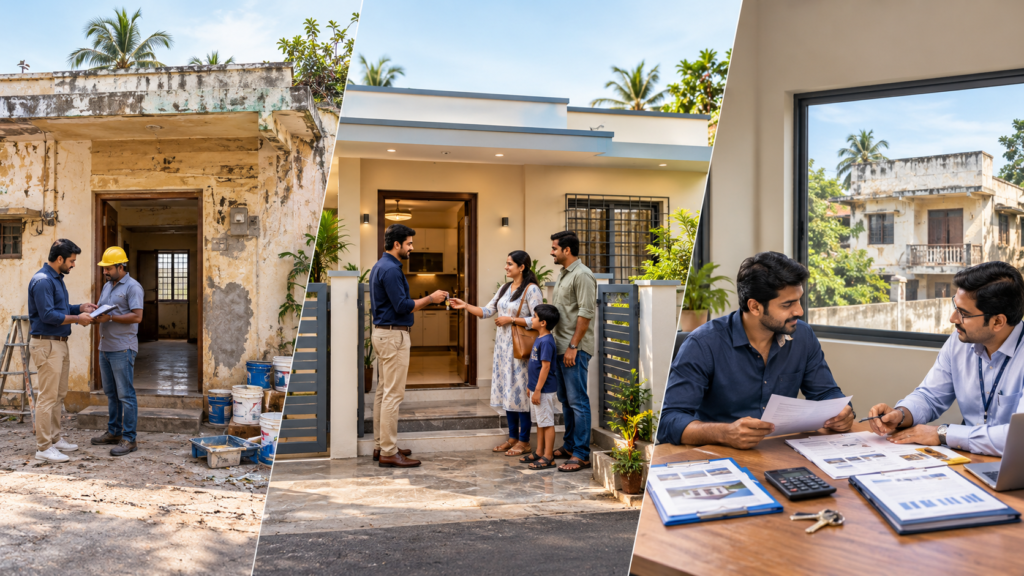
A property investor has two ways to look at an old house. One person sees peeling paint, outdated rooms, repair bills, and extra work. Another sees an opportunity to buy below the value of a similar finished property, improve it, and turn it into a rental asset.
The second approach is close to the thinking behind the BRRR strategy.
BRRR means Buy, Rehab, Rent, and Refinance. Instead of stopping after purchasing or renovating a property, the investor tries to turn the improved property into a source of rental income and recover part of the capital through a later refinance.
Start With the Property, Not the Strategy
The first step is finding a property where the numbers have potential. Suppose an older house is priced lower because it needs repairs. That discount may look attractive, but the purchase price is only one part of the calculation.
Work out the likely cost of renovation, financing, taxes, registration and other expenses. Then estimate what the property could reasonably be worth after the work.
Leave Room for Unexpected Costs
Renovation estimates rarely remain perfectly unchanged. A damaged pipe, electrical issue or structural repair can increase the budget. Keep a contingency amount instead of assuming every expense will match the original estimate.
Improve What Tenants Actually Need
The renovation stage should have a purpose. You might repair damaged flooring, repaint the property, improve a bathroom, update the kitchen or fix essential electrical and plumbing work.
The goal is not to create the most expensive property in the neighbourhood. It is to make the property functional and attractive enough for the intended rental market.
Study the Local Rental Demand
Before spending money on improvements, find out what tenants in that area actually want. A property can look excellent and still struggle to attract tenants if the location, size or rent does not fit local demand.
Turn the Property Into a Rental Asset
Once the work is finished, find a suitable tenant and monitor how the property performs. Keep track of rent received as well as loan payments, maintenance, vacancies, taxes, insurance and other ownership expenses.
This gives you a clearer picture of whether the property is producing useful cash flow.
Then Consider Refinancing
After the property has been improved and established as a rental, the investor can speak with lenders about refinancing.
The lender may assess the property’s current value, the borrower’s financial position, existing debt and other lending conditions. If refinancing is approved, the new loan may allow the investor to access some of the property’s equity.
This Is Where the Cycle Can Continue
The released capital may potentially be used toward another property. That creates the “Repeat” part of the broader BRRR approach.
However, this should not be treated as guaranteed. A lower valuation, stricter lending conditions, higher interest costs, or insufficient rental income can change the outcome.
Does BRRR Always Work?
No. The strategy depends heavily on buying at the right price, controlling renovation expenses, finding sufficient rental demand and obtaining workable financing. A simple test is this: if the investment only works under perfect conditions, it probably isn’t a strong deal.
Run the numbers using realistic rent, realistic repair costs and a conservative property valuation before committing your money.